
Summary:
You already know there’s damage. Maybe a storm came through last week. Maybe you noticed a stain on the ceiling and went up to look. Either way, you’re not really searching for a price — you’re searching for reassurance that insurance is going to cover this. That’s the part nobody explains clearly. Roof inspection cost in Monmouth County typically runs between $100 and $320, averaging around $240. But the cost of the inspection isn’t the issue. What that inspection produces — and when it happens — is what determines whether your claim gets paid in full, gets underpaid, or gets denied outright.
What Insurance Adjusters Actually Look for During a Roof Inspection
When an adjuster shows up, they’re not there to help you build a case. They’re there to document what they find and write a report that reflects their employer’s interests. That’s not cynical — it’s just how the process works. Understanding what they’re looking for gives you a real advantage going in.
Adjusters are trained to distinguish storm-caused damage from gradual wear. Those are two very different things under your policy, and the line between them is where most claims get complicated. Storm damage gets covered. Normal aging doesn’t. The adjuster’s job is to figure out which category your roof falls into — and if you haven’t already documented the damage yourself, their report becomes the official record of what happened.
Insurance Adjuster Roof Inspection: What They're Measuring and Why It Matters

For hail damage, adjusters look for circular impact marks on shingles, dents on soft metals like flashing and gutters, and granule displacement concentrated around the impact points. They’ll typically count the number of hits in a defined test square and extrapolate from there. Hail damage has a specific pattern — uniform across the roof slope, corresponding to the storm’s direction — and experienced adjusters know what it looks like. So do experienced roofing contractors.
Wind damage shows up differently. Lifted shingles, broken sealant strips along the edges, missing tabs, and creasing along the leading edge of a shingle field are all indicators. Wind damage tends to concentrate on one slope — usually the side facing the prevailing storm direction — rather than distributing evenly across the roof.
What adjusters also look for, and what homeowners often don’t anticipate, is anything they can use to classify damage as pre-existing. Cracked caulking around flashing, widespread granule loss that predates the storm, lifted shingles that show signs of long-term curl rather than sudden uplift — all of these give the adjuster room to argue that the damage wasn’t caused by a specific covered event. That argument is much harder to make when a professional inspection report, dated before the adjuster visit, already documents the condition of the roof immediately after the storm.
In coastal Monmouth County towns like Long Branch, Sea Bright, and Manasquan, this matters more than most homeowners realize. Salt air accelerates granule loss on asphalt shingles and speeds up flashing deterioration. An adjuster can point to that and call it coastal wear. A detailed inspection report that correlates specific damage patterns to a documented storm event counters that argument with evidence rather than opinion.
The other factor adjusters consider is roof age. Roofs over 20 years old may see 10–20% higher insurance premiums, and claim payouts can drop significantly due to depreciation. Many carriers switch older roofs from replacement cost value coverage — which pays what it costs to replace the roof today — to actual cash value, which subtracts depreciation and can produce a payout far below what the work actually costs. Knowing where your roof stands before the adjuster arrives gives you time to prepare, not scramble.
Should You Have a Contractor Present When the Adjuster Inspects Your Roof?
Yes — and most homeowners don’t know they’re allowed to. You have every right to have your own roofing contractor present when the insurance adjuster inspects your roof. Claims where a contractor is present during the adjuster visit consistently produce more complete initial scopes than claims where the homeowner is the only party present. That difference in scope translates directly into a difference in settlement amount.
Here’s why it matters in practice. Adjusters work quickly. They’re covering a lot of roofs, especially after a major storm event moves through Monmouth County. A thorough contractor who knows what storm damage looks like — and knows how to document it — will catch things an adjuster moving at pace might miss or record differently. Lifted flashing in a valley, a hairline crack along a ridge cap, granule loss concentrated on the south-facing slope consistent with the storm’s track: these details belong in the initial scope, not in a supplement you have to fight for later.
The other reason to have a contractor present is documentation continuity. If the same contractor who inspected your roof immediately after the storm is standing on that roof with the adjuster, their inspection report and the adjuster’s observations are happening in the same context. There’s no gap for the insurer to question whether conditions changed between the storm and the adjuster visit.
For homeowners in towns like Marlboro, Holmdel, Middletown, and Red Bank — where older housing stock means a lot of roofs are already carrying some age-related wear — having a contractor who can clearly distinguish storm-caused damage from background aging is especially valuable. The difference between a full replacement claim and a partial repair payout can come down to how precisely that line is drawn in the documentation.
Roof Claim Denied? Here's Why It Usually Happens Before the Storm
Most homeowners assume a denied roof claim means the damage wasn’t real, or the storm wasn’t bad enough. In reality, the most common reasons for denial have nothing to do with the storm itself. They’re about conditions that existed before the storm — and whether the homeowner can prove otherwise.
Insurance policies cover sudden and accidental damage. They don’t cover the results of neglect, deferred maintenance, or prior repairs that weren’t done to code. If an adjuster can point to evidence of any of those things, the denial has a foundation — even if a legitimate storm event clearly occurred.
Most Common Reasons Roof Insurance Claims Get Denied in New Jersey
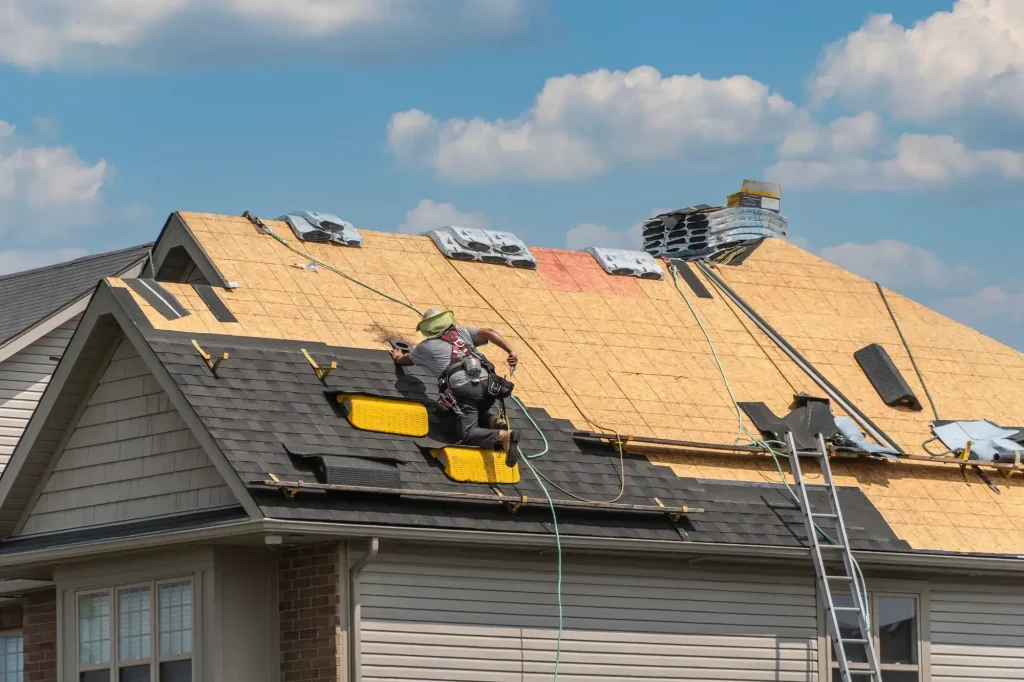
Pre-existing damage is the most common denial ground, and it’s also the most preventable. If your roof had cracked flashing, failing sealant, or deteriorated shingles before the storm hit, an adjuster can argue that the damage you’re claiming predates the covered event. Without a professional inspection report showing the roof’s pre-storm condition, you have no evidence to counter that argument.
Lack of maintenance records is closely related. Insurance companies expect homeowners to take reasonable steps to maintain their roofs. If there’s visible evidence of long-term neglect — moss growth, accumulated debris in valleys, fascia rot, gutters pulling away from the roofline — the adjuster has grounds to attribute damage to neglect rather than storm impact.
Prior non-code repairs are a less obvious but equally serious problem. If a previous contractor patched your roof using improper materials, skipped required permits, or did work that doesn’t meet the International Code Council standards adopted locally in New Jersey, coverage on the affected area can be voided. This is one of the clearest reasons to verify that any contractor you hire is a registered NJ Home Improvement Contractor — the license number format is 13VH followed by digits, and it’s verifiable through the NJ Division of Consumer Affairs.
Missed filing deadlines catch homeowners off guard more often than you’d expect. Most policies have a strict timeframe for reporting damage after a storm. If you wait too long — even if the damage is real and clearly storm-related — the insurer has grounds to deny on procedural grounds alone. After any significant storm event in Monmouth County, getting a professional inspection on the calendar quickly isn’t just good practice. It’s part of protecting your claim.
Finally, insufficient documentation sinks more claims than homeowners realize. Phone photos help, but they’re not a substitute for a professional inspection report with a line-item scope, measurements, and clear correlation to a documented storm event. No professional report, no NWS storm record, no documentation of when the damage was first observed — that combination gives the adjuster room to question whether the damage came from a specific covered event at all.
Working With a Roofing Company on an Insurance Claim: What the Process Should Look Like
The most important thing to understand about working with a roofing company on an insurance claim is the sequence. Call your contractor before you call your insurance company. Not after — before. A trusted local roofer will inspect your roof, tell you whether you have legitimate claimable damage, and document what they find. That documentation becomes your evidence. If you call the insurer first and an adjuster arrives before you’ve had an independent inspection, the adjuster’s report is the first official record of what your roof looks like. That’s a disadvantage you don’t need to start with.
A good roofing company will also help you understand what your claim is realistically worth before you file. In Monmouth County, a typical NJ wind or hail deductible runs between 1% and 5% of your dwelling value. On a $400,000 home, that’s $4,000 to $20,000 out of pocket before insurance covers anything. Knowing that number upfront — and knowing whether the scope of damage actually justifies filing — protects you from filing a claim that costs you more in future premium increases than it pays out.
What you want from a roofing company in this process is straightforward: a thorough on-roof inspection, a written report that documents damage type, extent, and probable cause, and a contractor who will be present when the adjuster arrives. That last part is where a lot of contractors fall short. Many will inspect and write a report, then leave the adjuster visit entirely to you. The difference between a contractor who shows up for the adjuster visit and one who doesn’t can be thousands of dollars in your final settlement.
We’ve been doing this in Monmouth County for over 40 years. We’ve seen how storms move through this area — the nor’easters that hit the coast hard from Sea Bright to Manasquan, the hail events that track through Freehold and Marlboro, the wind damage that shows up differently on a Colts Neck colonial than it does on a beachfront property in Long Branch. That experience doesn’t just help us find damage. It helps us document it in a way that holds up when the adjuster is standing on the same roof.
Our owner is present at every job, including inspections. We’re licensed and insured under NJ HIC Registration #13VH13248500. When you call A Russo Roofing & Siding, you get a same-day free estimate — not a call center, not a scheduling queue, not a crew without anyone accountable on site.
Roof Inspection Cost in Monmouth County, NJ: The Real Question to Ask
Roof inspections in Monmouth County typically run between $100 and $320, averaging around $240. That number matters a lot less than what the inspection produces and when it happens. A professional report, prepared before the adjuster arrives, is the single most effective thing you can do to protect your claim outcome.
The homeowners who get underpaid — or denied — usually aren’t the ones with the worst damage. They’re the ones who didn’t have documentation in place when it counted. The claims process moves fast once you open it, and the adjuster’s report carries real weight.
If you’ve had recent storm damage, or you’re not sure whether what you’re seeing on your roof qualifies as a claim, reach out to A Russo Roofing & Siding for a same-day free estimate. We’ve been serving Monmouth County homeowners for more than four decades, and we’ll get the documentation started before the adjuster does it for you.