
Summary:
A storm rolls through Monmouth County. You walk outside the next morning and something looks off — a few shingles are missing, the gutters are bent, or there’s a ceiling stain you’ve never noticed before. Your first instinct is to call your insurance company. That instinct is understandable, but it may be the one move that costs you the most money.
The roof insurance claim process in New Jersey isn’t complicated once you understand it — but the sequence matters. What you do before you call your insurer can be the difference between a full payout and a check that barely covers your deductible. Here’s what you actually need to know.
What's Actually Covered Under a Monmouth County Homeowners Policy
Most standard homeowners insurance policies in New Jersey cover sudden, storm-caused damage — things like hail, high winds, and falling debris. What they don’t cover is gradual wear, age-related deterioration, or damage that was already there before the storm hit. That distinction matters a lot when you’re trying to figure out whether you have a claim worth filing.
Hail is the most common trigger for roof insurance claims across Monmouth County. The region consistently experiences severe thunderstorms, and inland communities like Freehold, Manalapan, Howell, and Marlboro sit directly in a documented severe thunderstorm corridor where one-inch or larger hailstones aren’t unusual. Wind and hail together account for roughly 41% of all homeowners insurance claims in the country, according to the Insurance Information Institute.
How to Tell If Your Damage Qualifies for a Claim

Here’s something most homeowners don’t realize: hail damage isn’t always visible from the ground. Small to mid-sized hailstones can bruise shingles and displace the granules that protect them from UV exposure and water — and none of that shows up as a leak right away. The roof looks fine from the street. But six months or a year later, those compromised shingles start to fail, and by then the connection to the original storm is harder to prove.
This is exactly why getting a contractor inspection before you call your insurance company is the single most important step in the process. Not after the adjuster comes. Before. When you have a written, itemized damage report in hand before the claims process starts, you walk in with documentation — not just a story. The adjuster works for the insurance company, not for you. Having a professional assessment already on record changes the dynamic of that conversation entirely.
Not every roof problem is a valid insurance claim. If your shingles are 20 years old and starting to curl at the edges, that’s age. If a hailstorm just rolled through and your 20-year-old shingles now have impact craters and granule loss, that’s a storm event — and it may well be covered, even on an older roof. The cause matters more than the age, though age does affect how much you receive under certain policy types.
The window to document damage properly is short. After any significant storm in Monmouth County, delaying inspection by even a few weeks can make it harder to tie the damage to a specific event, especially if another storm passes through in the meantime.
ACV vs. RCV: Understanding Your Payout
If there’s one piece of insurance terminology worth understanding before you file, it’s the difference between Actual Cash Value (ACV) and Replacement Cost Value (RCV). These aren’t just technical definitions — they directly determine how much money ends up in your pocket.
An RCV policy pays for the cost of replacing your damaged roof with a comparable new one, minus your deductible. An ACV policy pays for that same replacement, minus depreciation based on the age and condition of your existing roof. On a 15-year-old asphalt shingle roof, that depreciation can be substantial — sometimes cutting your payout by 40 to 50 percent compared to what the actual repair or replacement costs.
Many homeowners don’t know which type of policy they have until they’re already in the middle of a claim. If you have an ACV policy and your roof is older, you could receive a check that covers only a portion of the job — and be responsible for the rest out of pocket. That’s not the insurance company doing anything wrong; it’s just how ACV policies work. But it’s information you need going in, not after the fact.
There’s also the question of wind and hail deductibles. Some NJ homeowners policies carry a separate, higher deductible specifically for wind and hail claims — often expressed as a percentage of the home’s insured value rather than a flat dollar amount. On a home insured for $400,000 with a 2% wind/hail deductible, that’s $8,000 out of pocket before coverage kicks in. This doesn’t mean you shouldn’t file — it means you need to understand the math before you do.
We can review your damage, give you a realistic scope of what needs to be done, and help you understand whether the numbers make sense to file. That conversation costs you nothing — and it gives you the information you need to make a smart decision.
The Right Way to File Your Roof Insurance Claim
Once you’ve confirmed that you likely have storm-caused damage and understand the basics of your coverage, the process itself is fairly straightforward — as long as you follow it in the right order.
Start by documenting everything you can safely access from the ground. Photos and video of visible damage, dented gutters, damaged vents, and any debris are all useful. Then get a licensed NJ contractor out for an inspection before you contact your insurer. That written report becomes your baseline. From there, you file the claim, and the insurance company sends an adjuster to assess the damage. The critical move at this stage: make sure your contractor is on the roof at the same time the adjuster is. Not after. Not before. At the same time.
What to Do in the First 24 to 48 Hours After Storm Damage
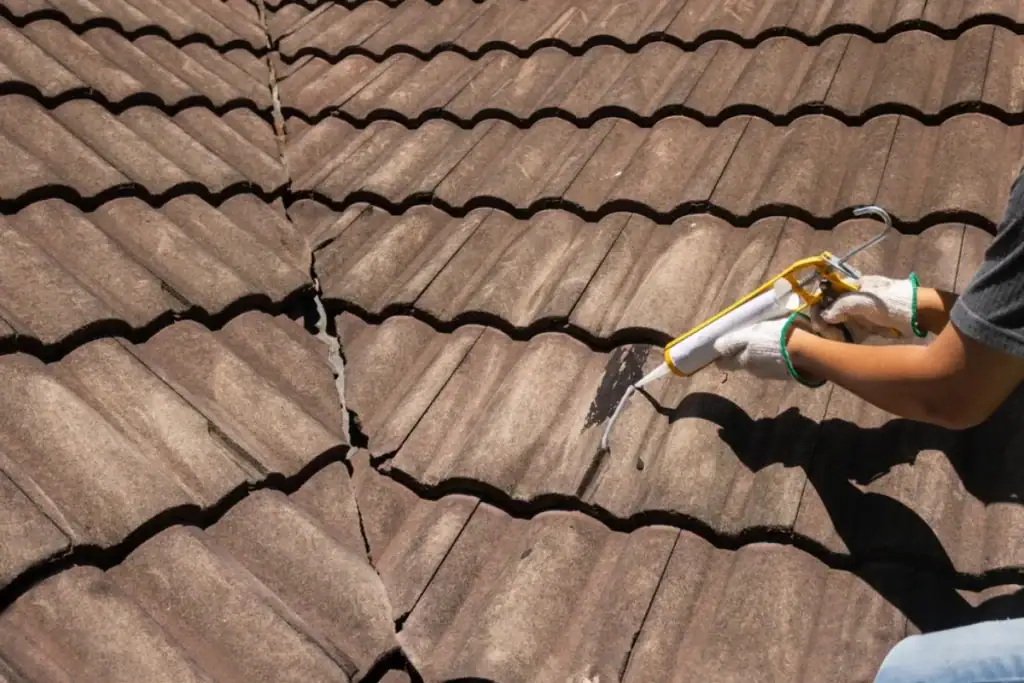
The first 24 to 48 hours after a storm are the most important window in any roof insurance claim. Water intrusion compounds quickly — what starts as a few missing shingles can become a damaged deck, ruined insulation, and mold if it’s not addressed. And the longer you wait to document, the harder it becomes to tie specific damage to a specific storm.
If there’s active water intrusion, emergency tarping is the right first move. This is a legitimate, reimbursable expense under most homeowners policies — it prevents further damage and demonstrates that you acted responsibly to mitigate the loss. Keep any receipts.
After that, get a licensed contractor on the roof. In New Jersey, all roofing contractors are legally required to hold a Home Improvement Contractor (HIC) license through the NJ Division of Consumer Affairs. You can verify any contractor’s license number on the Division’s website before you let anyone on your roof. This matters especially after major storms, when out-of-state “storm chaser” crews move into areas like Monmouth County looking for quick work — often collecting deposits and delivering substandard results, or disappearing entirely.
A contractor who has been operating in Monmouth County for decades knows the local storm patterns, knows which damage types the insurance companies in this area scrutinize most closely, and knows how to document a claim in a way that holds up. That local knowledge isn’t a small thing. It’s the difference between a scope of work that gets approved and one that gets pushed back.
Once you have your contractor’s written assessment, call your insurance company to open the claim. Give them the documentation you already have. Don’t speculate about the cause or extent of damage — let the written report do that work for you.
What to Do If Your Adjuster's Offer Is Too Low
This is where a lot of homeowners feel stuck. The adjuster comes out, writes a scope, and the settlement offer arrives — and it’s thousands of dollars less than what your contractor said the job will actually cost. It happens more often than you’d think, and it happened to a lot of Monmouth County homeowners after major storm events over the years, including in the wake of Hurricane Sandy in 2012.
You have options. The first is straightforward: have your contractor provide a detailed written rebuttal to the adjuster’s scope, line by line, with documentation. Many underpaid scopes get corrected at this stage when a contractor pushes back with specific evidence — test square counts by roof slope, photos of each impact point, identification of the shingle product and its vulnerability to the specific hail size that fell.
If that doesn’t resolve the gap, most NJ homeowners policies include an appraisal clause. This formal process allows either party — you or the insurance company — to request an independent appraisal when there’s a dispute over the value of the damage. Each side selects an appraiser, those two appraisers select a neutral umpire, and the umpire’s decision is binding. It’s not litigation, it’s not adversarial in the way a lawsuit would be, and it frequently results in a higher settlement than the original offer.
What you want to avoid is signing anything that transfers control of your claim away from you before you fully understand the terms. Some contractors ask homeowners to sign an Assignment of Benefits (AOB) form — this hands over your claim rights to the contractor. In some situations that’s fine, but you should understand what you’re signing before you do it, and you should never feel pressured to sign before you’ve had a chance to read the document.
A low adjuster offer is not the final word. Knowing that going in keeps you from leaving money on the table.
Working With A Russo Roofing & Siding on Your Insurance Claim
Filing a roof insurance claim doesn’t have to be a stressful guessing game — but it does require knowing the right sequence, understanding your policy, and working with someone who has actually done this before in your area.
Monmouth County gets hit hard by hail and wind every year. The inland towns deal with severe convective storms; the coastal communities deal with Atlantic wind exposure and nor’easters. The damage looks different, the documentation requirements are specific, and the insurance companies active in this market have patterns that we already know how to navigate.
We’ve been doing this work in Monmouth County for over 40 years. If a storm has hit your home and you’re not sure where to start, the best first call is to us — before you call your insurer, before you sign anything, and before anyone else gets on your roof.